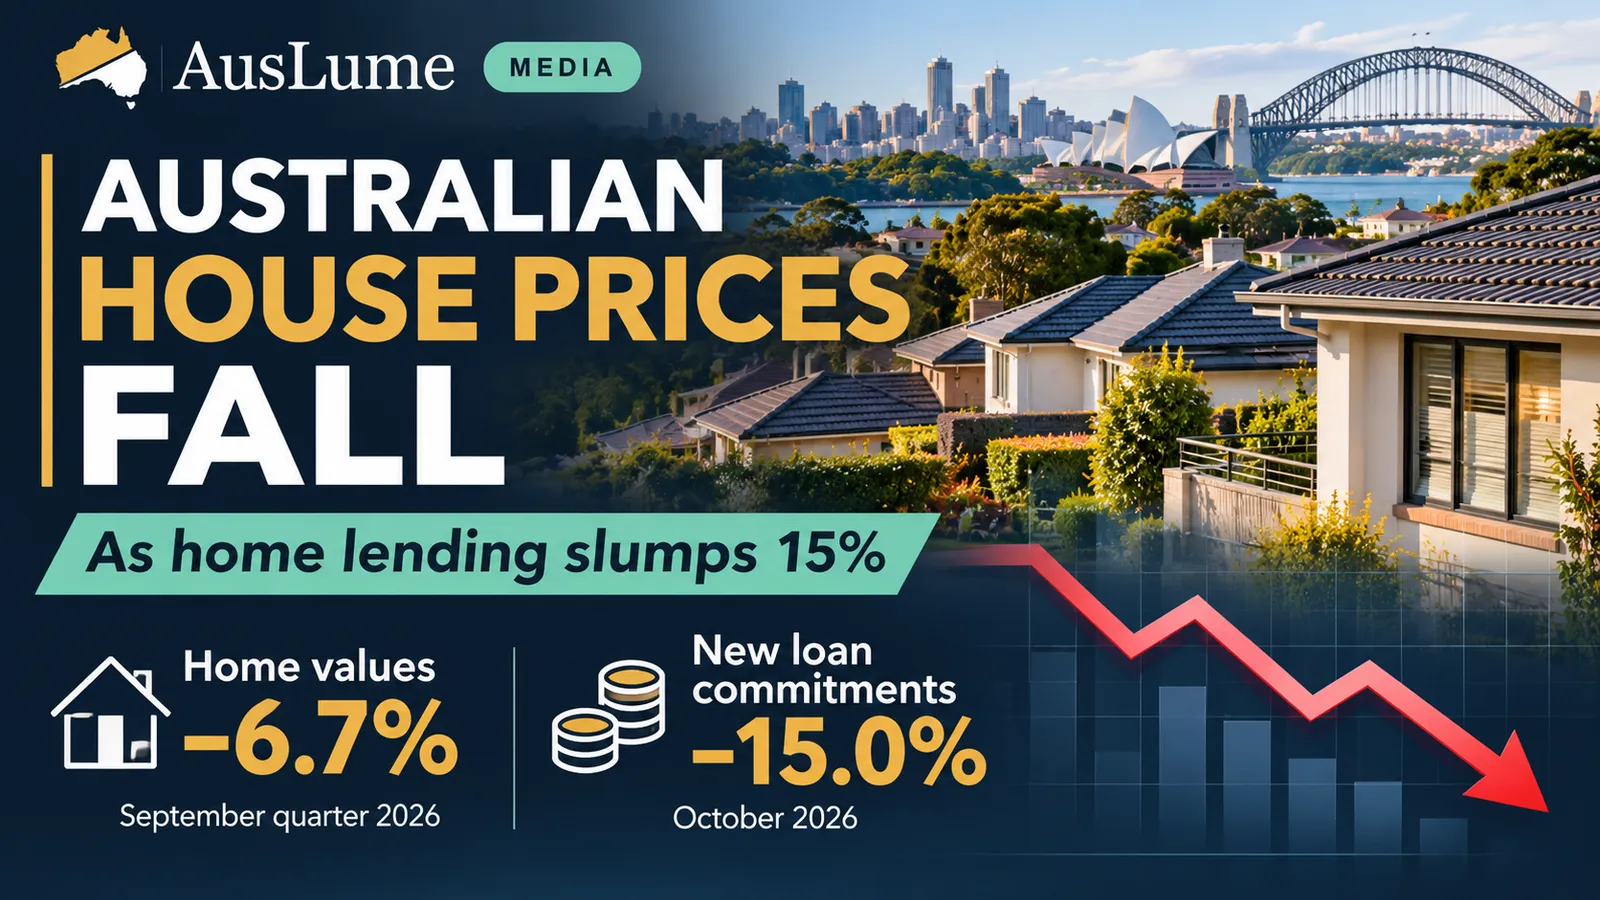
Australia's property market is experiencing one of its sharpest downturns in decades. National dwelling values fell 1.2 per cent in October, marking seven consecutive monthly declines. Meanwhile, new housing loan commitments dropped 15 per cent in the September quarter, according to the Australian Bureau of Statistics (ABS).
The downturn is being driven by higher interest rates, reduced borrowing capacity and changes to property investment taxation. While falling values may create opportunities for some buyers, they also introduce risks for existing homeowners and the wider economy.
Key points
Australian dwelling values fell 6.7 per cent from their March 2026 peak, according to Cotality.
The median Australian dwelling lost approximately $63,400 in value over that period.
New home loan commitments declined 15 per cent in the September quarter.
Investor loan commitments dropped 30.6 per cent, a record quarterly fall.
The Reserve Bank increased the cash rate target to 4.85 per cent in November.
Major banks expect further property price declines, although forecasts remain uncertain.
Australian house prices fall for a seventh consecutive month
Australia's housing market has undergone a significant change since March 2026.
Cotality's October Home Value Index recorded a 1.2 per cent monthly decline in national dwelling values. The index was 6.7 per cent below its March peak.
That represents an estimated $63,400 reduction in the value of the median Australian dwelling.
According to ABC News reporting on Cotality's figures, the national median dwelling value stood at approximately $884,855 at the end of October.
The downturn is no longer limited to Sydney and Melbourne. Previously stronger markets, including Brisbane, Perth and Adelaide, are experiencing weaker conditions.
National Australia Bank's November Housing Monitor reported that dwelling values across the combined capital cities had fallen 8.1 per cent from their March peak.
NAB's figures also showed Sydney down 10.1 per cent from its peak and Melbourne down 7.8 per cent.
These figures use specific market measures and should not be treated as interchangeable with national median prices.
Why are Australian house prices falling?
Several factors are contributing to the downturn.
1. Higher interest rates are reducing borrowing capacity
The Reserve Bank of Australia increased its cash rate target by 0.25 percentage points to 4.85 per cent on 3 November 2026.
The increase followed four earlier rate rises during the year.
Higher interest rates increase borrowing costs and can reduce the amount banks are prepared to lend to prospective homebuyers.
For example, a household that previously qualified for a particular loan may now be approved for a smaller amount because the repayments would be higher.
This puts downward pressure on housing demand, particularly in expensive property markets.
2. Property investors are retreating
New ABS figures show that investor lending has declined significantly.
The number of new investor loan commitments fell 30.6 per cent in the September quarter, reaching 35,301.
The value of investor lending declined 32.3 per cent over the same period.
Both represent the largest quarterly falls recorded in their respective series.
By comparison, the number of new owner-occupier commitments fell 5.3 per cent.
The difference suggests investors are responding more strongly to changing market conditions.
3. Housing tax reforms are changing investment decisions
The federal government's 2026–27 Budget introduced reforms to negative gearing and capital gains tax.
From 1 July 2027, negative gearing for residential property will generally be limited to newly built homes, with exemptions for properties held before the government's announcement on 12 May 2026.
Changes to capital gains tax arrangements are also scheduled to begin from July 2027.
The measures aim to direct investment towards new housing construction rather than competition for existing properties.
Although the new arrangements are not yet fully in effect, expectations about future tax treatment may already be influencing investor decisions.
The ABS has identified potential tax changes and expectations of lower property prices as factors contributing to weaker investment activity.
What does the housing downturn mean for first-home buyers?
Falling property values could help some Australians enter the housing market.
Lower purchase prices may reduce the deposit needed to buy a home. Buyers may also face less competition at auctions and have more time to consider available properties.
However, lower property prices do not automatically make purchasing easier.
Higher mortgage interest rates can offset some of the savings from a reduced purchase price.
Banks also assess income, expenses, existing debts and the applicant's ability to manage repayments.
The ABS reported that the number of new owner-occupier first-home buyer loan commitments fell 8.6 per cent in the September quarter.
This indicates that first-home buyers are also experiencing difficult borrowing conditions.
For prospective buyers, the improvement in purchase prices needs to be considered alongside financing costs and household financial security.
What happens to existing homeowners when property values fall?
For existing homeowners, the impact depends largely on when they purchased their property and how much they still owe.
Households that bought recently with smaller deposits may be more exposed to declining values.
A lower property valuation can reduce home equity, potentially affecting refinancing, upgrading or selling decisions.
However, a decline in a property's market value does not automatically change the owner's mortgage balance or require them to sell.
For established homeowners with substantial equity, short-term fluctuations may have less immediate impact.
The financial consequences become more significant when households need to sell, refinance or manage repayments under difficult circumstances.
Higher mortgage costs also mean some homeowners may be experiencing financial pressure even without selling their properties.
Are Sydney and Melbourne experiencing the biggest falls?
Sydney and Melbourne were among the earliest major markets to weaken.
According to NAB's November analysis, Sydney dwelling prices were 10.1 per cent below their recent peak by October.
Melbourne prices were 7.8 per cent below their peak.
The downturn has since spread to other capital cities.
NAB reported particularly weak monthly conditions in Brisbane and Perth during October, with both cities more than 8 per cent below their respective peaks.
This broadening correction suggests the downturn is being influenced by national economic and financial conditions, rather than problems confined to one city.
However, individual suburbs, property types and price ranges can behave differently from broader city averages.
Will Australian house prices fall further in 2027?
Several major financial institutions expect the downturn to continue.
Commonwealth Bank economists recently revised their forecast for the national peak-to-trough dwelling price decline from approximately 9 per cent to 14 per cent.
NAB has also forecast a decline of around 14 per cent from peak to trough across its capital-city housing measure.
These are economic forecasts, not confirmed future outcomes.
Property prices may respond differently depending on future interest rate decisions, inflation, employment, housing supply and buyer confidence.
The Reserve Bank has also acknowledged uncertainty about the broader economic effects of the housing downturn.
A recovery could take longer if borrowing costs remain elevated or household incomes weaken.
Could falling house prices help solve Australia's housing affordability crisis?
Lower purchase prices are one part of improving housing affordability, but they are not the only factor.
Household incomes, mortgage rates, rental costs and the availability of suitable homes also determine whether people can afford housing.
A substantial price correction could improve the position of some buyers. However, if it occurs alongside weaker employment or persistently high borrowing costs, the improvement may be limited.
Australia also faces longer-term challenges involving housing construction, planning approvals, infrastructure and the distribution of homes across cities and regional areas.
The national target of building 1.2 million additional homes over five years is intended to address housing supply, but delivery remains challenging.
Increasing supply may improve affordability over time without relying entirely on declining property values.
What should Australians watch next?
Several developments will help determine where the housing market goes from here.
Interest rate decisions: The Reserve Bank's next monetary policy announcement is scheduled for 8 December 2026.
Home loan activity: Upcoming ABS data will show whether lending continues to decline or begins to stabilise.
Monthly property prices: Future Cotality and other property index releases will help identify whether the downturn is slowing.
Housing construction: Building approvals and completion figures will provide insight into the country's longer-term housing supply.
Employment and household finances: Changes in job security and household income could affect mortgage repayments and demand for housing.
The bigger picture
Australia's housing market is at an important turning point.
After years of strong price growth, higher interest rates and changing investment incentives are placing pressure on property values.
For some prospective buyers, falling prices could create opportunities that were previously out of reach.
For existing homeowners, investors and businesses connected to the property sector, the downturn brings greater uncertainty.
The central question is whether Australia can achieve genuinely more affordable housing while maintaining financial stability and increasing the supply of homes needed for the future.
About the author
RullikClear, sourced explainers on Australia and the world
Rullik is the pen name of the founder of Australia Illuminate (Auslume). Rullik writes plain-language explainers on life in Australia, from immigration, study and work to money, sport and screen culture, always linking to the official sources behind each story. Every story is reviewed before publication.
More from Rullik ↗Sources
- https://www.abs.gov.au/media-centre/media-releases/largest-quarterly-falls-record-led-loans-investors
- https://www.abs.gov.au/statistics/economy/finance/lending-indicators/latest-release
- https://www.rba.gov.au/media-releases/2026/mr-26-30.html
- https://www.rba.gov.au/publications/smp/2026/nov/economic-conditions.html
- https://treasury.gov.au/policy-topics/taxation/budget2026-27
- https://miblinks.nab.com.au/news/housing/nab-housing-monitor-november-2026
- https://www.commbank.com.au/articles/newsroom/2026/11/home-prices-record-downturn-commbank-economists.html
- https://www.abc.net.au/news/2026-11-02/house-prices-fall-in-october-biggest-downturn-40-years-cotality/107325214
- https://www.abc.net.au/news/2026-11-14/do-australians-actually-want-cheaper-housing/107378812